FCCPA Florida Debt Collection: 6 Rights the FDCPA Lacks
FCCPA Florida Debt Collection: How Chapter 559 Protects You When Collectors Cross the Line
What You'll Learn
- Why the company that originally lent you money can break Florida law even though federal law doesn't apply to it
- The Florida rule debt buyers are supposed to follow before they collect, and why it gives you leverage
- How a Pine Hills renter's $2,100 collection dropped to $0 because of one missed landlord deadline
- What Florida lets a judge award against a collector that federal law doesn't
If a collector is calling you at 9:15 at night, calling your boss, or threatening to sue over a balance you know is wrong, stop taking it.
You live in Florida. That means you've got two sets of debt-collection laws in your corner, not one. Most people only know about the federal Fair Debt Collection Practices Act (FDCPA). The real leverage on FCCPA Florida debt collection problems sits in the state law most collectors hope you've never heard of: the Florida Consumer Collection Practices Act, found in Chapter 559 of the Florida Statutes.
I'm Matt Brody. I've run Freedom Credit Repair out of Orlando since 2019, and I'll tell you straight: the FCCPA is the best tool Florida consumers have that almost nobody uses.
Let's fix that.
The Problem: Collectors Count on You Knowing Only Half the Rules
Here's the thing about the federal FDCPA. It's a good law, but it has a giant hole in it.
The FDCPA mostly covers third-party debt collectors. It doesn't generally cover the original creditor collecting its own debt. That means your apartment complex, your dentist, your hospital billing office, or the credit card company itself can usually act ugly without triggering the federal law.
Sound familiar? Plenty of the worst calls I hear about come straight from the original creditor.
Florida closed that gap years ago. The FCCPA applies to any person collecting a consumer debt, original creditors included. (Yes, really. Your landlord counts.)
Meet my Pine Hills client
I had a client in Pine Hills who broke her apartment lease early. She needed to move closer to her mom after a job change, she gave notice, and she left the unit clean.
A few months later she got a collection letter. $2,100 in unpaid rent. Then the account showed up on all three credit reports.
Know what the kicker was? The complex never credited her security deposit. And a new tenant moved into that same unit two weeks after she left, paying rent the whole time. The complex basically tried to collect rent twice on the same apartment and keep her deposit too.
She almost paid it. She figured fighting would cost more than the debt. Hold that thought — I'll show you how this ended in the action plan.
What Happens If You Do Nothing
I hate when people ignore their mail. It never makes the debt go away. It just hands the collector the steering wheel.
Here's what can realistically happen in Florida if you sit on it:
- The collection stays on your credit reports. Under federal law, a collection can report for about seven years from when you first fell behind (technically seven years plus 180 days from the start of the delinquency). That can mean higher rates or flat denials on car loans, apartments, and mortgages.
- You could get sued in county court. Small balances like a $2,100 rent claim typically land in county court in Orange, Osceola, or Seminole County. Collectors file these in batches. Not sure if you've already been sued? Search your own name on the Orange County Clerk's site (myorangeclerk.com) or the Osceola or Seminole clerk sites. Takes two minutes.
- A default judgment. You generally get 20 days after service to respond to a Florida lawsuit. Miss it and the collector can ask the clerk for a default. No defense, no hearing, no argument about the inflated balance.
- Wage garnishment or a bank levy. Once the collector has a judgment, it can try to garnish wages or freeze a bank account.
Now, real talk — Florida isn't defenseless territory. If you're a head of family (you provide more than half the support for a child or other dependent), Fla. Stat. § 222.11 shields a big chunk of your wages, and the Florida Constitution's homestead protection generally keeps a judgment creditor from forcing the sale of your primary home. But you have to claim those exemptions. They don't kick in automatically. I've watched a single dad from Kissimmee lose two paychecks before anyone told him to file a claim of exemption.
And the statute of limitations? Florida generally gives creditors five years on written contracts and four years on many open accounts and contracts that aren't in writing (Fla. Stat. § 95.11). Which one applies depends on the paperwork behind your debt, so don't assume. That's a long runway for a collector to wait you out.
FCCPA vs FDCPA in Florida: Your Legal Leverage
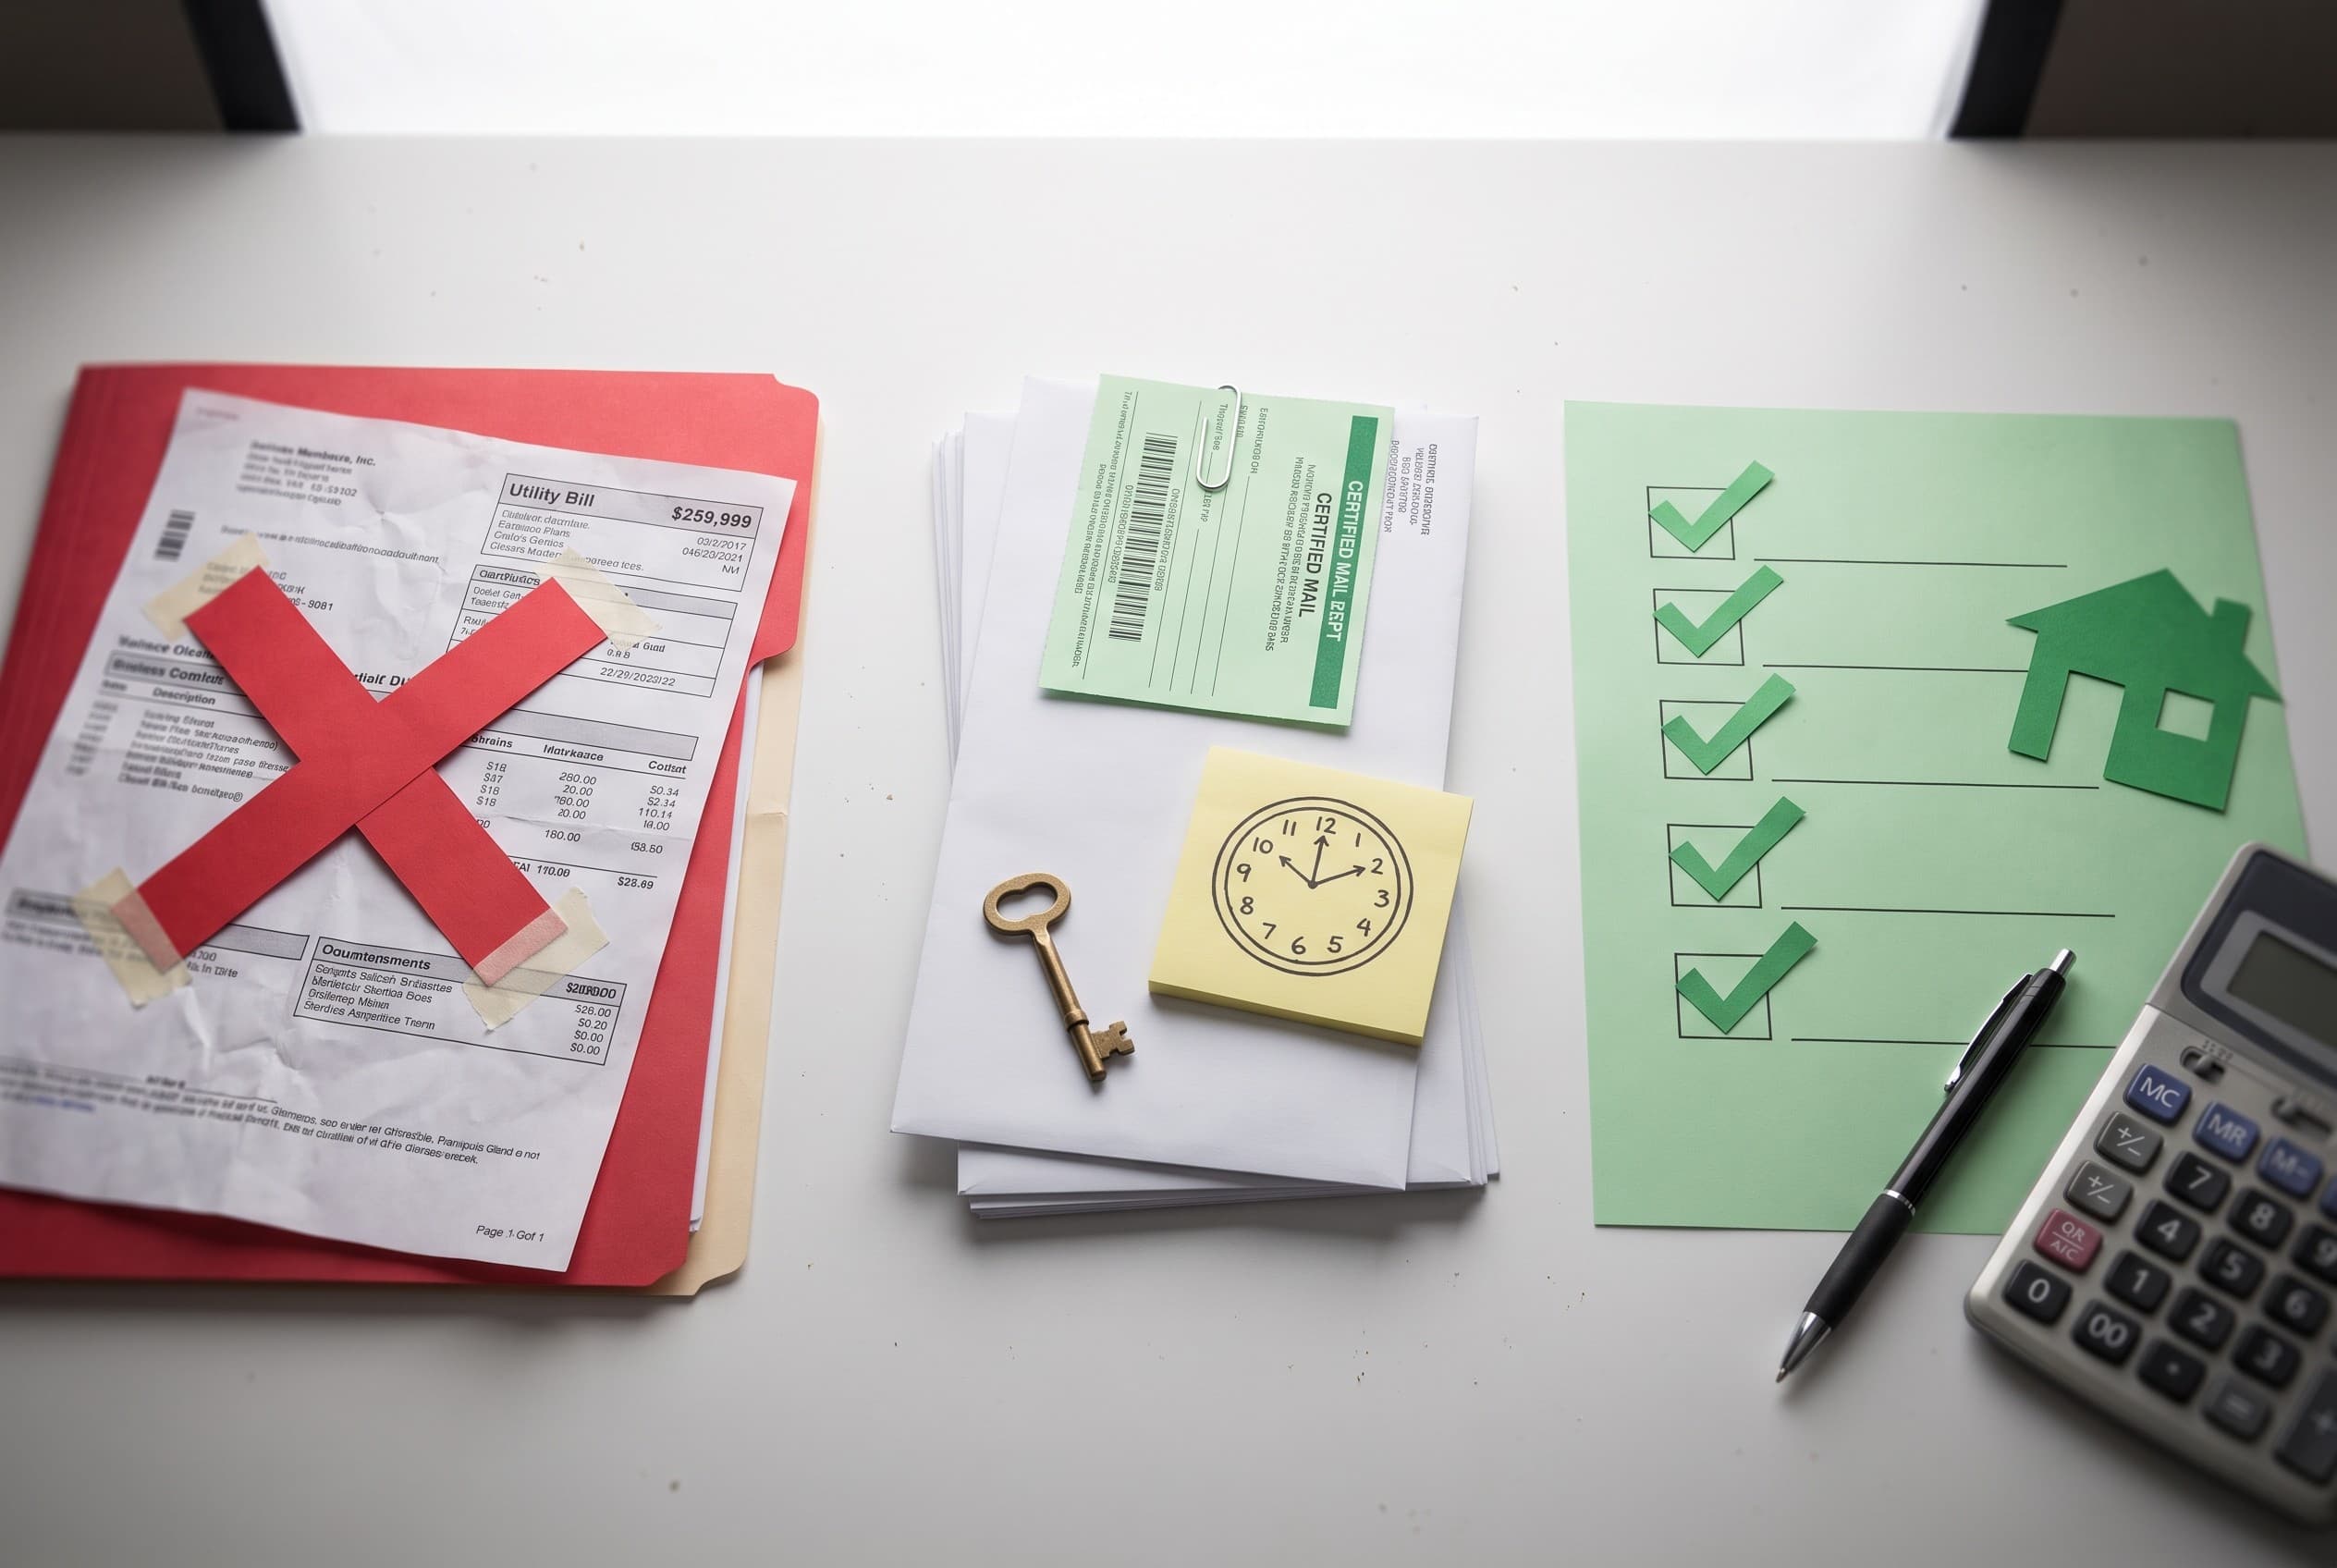
OK so, here's where it gets interesting. The FCCPA doesn't replace the federal law. Florida's statute says the two work side by side, and where Florida's rule protects you more, Florida's rule applies. That's in § 559.552.
So you get the federal FDCPA rights, like the right to request debt validation under 15 U.S.C. § 1692g, plus everything Chapter 559 adds on top.
Here's the side-by-side I walk clients through:
| Issue | Federal FDCPA | Florida FCCPA (Ch. 559) |
|---|---|---|
| Who it covers | Mostly third-party collectors | Any person, including original creditors |
| Time to sue | 1 year from violation | 2 years from violation |
| Statutory damages | Up to $1,000 | Up to $1,000 |
| Punitive damages | Not provided | Court may award |
| Attorney's fees | Yes (and courts can award fees against you if you sue in bad faith or to harass) | Yes (and courts can award fees against you on a frivolous claim) |
| Collector licensing | No federal registration | Consumer collection agencies must register with Florida's Office of Financial Regulation |
Right #1: Original creditors are on the hook
This one's the big one. Under § 559.72, Florida says that no person collecting a consumer debt may commit the prohibited practices. That's your landlord, your hospital, your car dealer's in-house finance arm. Not just the agency in another state with a robocall dialer.
Right #2: No pretending a fake debt is real
Section 559.72(9) bars anyone from claiming, attempting, or threatening to enforce a debt when they know it isn't legitimate, or asserting a legal right they know doesn't exist. Hands down, this is the subsection I lean on most for inflated balances — padded fees, double-billed rent, charges already paid.
Right #3: Quiet hours and harassment limits
Under § 559.72(17), collectors generally can't contact you between 9 p.m. and 8 a.m. your time without your permission. The federal FDCPA uses the same hours — but only against third-party collectors. Florida's rule reaches your landlord and your hospital billing office too. That's the difference. Collectors also can't call with such frequency that it's reasonably expected to harass you, use profane language, or threaten violence.
On the federal side, the CFPB's Regulation F adds a presumption that more than seven calls in seven days about one debt crosses the line. The CFPB explains the call limits here. Stack the two and you've got a solid record when a collector goes nuclear on your phone.
Right #4: Your boss stays out of it
Under § 559.72(4), Florida generally bars collectors from contacting your employer about the debt before obtaining a final judgment, unless you've given permission or you're the one who asked them to call. And under § 559.72(5), they can't share info that hurts your reputation with people who don't have a legitimate business need to know.
One catch I won't hide from you: that reputation rule specifically carves out your family. So Florida doesn't wall off your relatives the way it does your boss. If a collector's calls to family turn harassing, though, the harassment rules still apply.
Right #5: Disputed means disputed
If a collector shares information about a debt it knows you're disputing, and it doesn't disclose the dispute, that's a problem under § 559.72(6). Pair that with the federal FCRA requirement (FCRA § 623, 15 U.S.C. § 1681s-2) that furnishers report disputed accounts as disputed, and you've got two angles.
Right #6: Debt buyers have to tell you first
This is the operator-level detail most people miss. Under § 559.715, when a debt gets assigned to a new owner, the assignee has to give you written notice of the assignment as soon as practical and at least 30 days before taking any action to collect.
In my experience, debt buyers that bought a file in a bulk portfolio sometimes jump the gun. When we see a lawsuit or aggressive collection with no prior assignment notice in the client's paper trail, we flag it immediately.
Straight talk, though: Florida courts don't agree on whether a missing assignment notice actually kills a lawsuit. Some judges have treated it as a required step before suing. Others have said it doesn't give you a standalone defense. So it's strong leverage in a dispute — but don't bet your whole case on it in court.
What the FCCPA pays — and what it doesn't
Under § 559.77, a court may award:
- Your actual damages
- Additional statutory damages up to $1,000
- Punitive damages in the court's discretion
- Court costs and reasonable attorney's fees
Now let me be straight with you, because I won't sell you a fantasy. None of that is automatic. A collector can raise a bona fide error defense if it shows the violation wasn't intentional and it had procedures in place to prevent it. And if a court finds your lawsuit lacked a justiciable issue, it can make you pay the collector's attorney's fees. That's a real risk, so talk to a consumer attorney before filing suit.
The bottom line? The FCCPA gives you leverage, not a lottery ticket. Used right, it gets collectors to correct balances, stop calling, and fix their reporting.
The Action Plan: How to Use Chapter 559 Against a Florida Collector
Here's the playbook I run with clients. You can do every single step yourself, for free.
Step 1: Start a call log today
No-brainer, but almost nobody does it. For every call, write down:
- Date and exact time (that 9:12 p.m. call matters)
- Number and company name
- What they said, word for word if you can
- Who else heard it — spouse, coworker, roommate
Screenshot your call history weekly. Phones purge old logs, and I've lost good evidence for clients that way.
Step 2: Demand validation in writing
Send a written dispute and validation request within 30 days of getting the collector's validation notice to lock in your federal § 1692g rights. Ask for:
- The original creditor and account number
- An itemized balance — principal, interest, fees, and credits
- Proof of the collector's right to collect (assignment documents)
- The collector's Florida registration, if it's a consumer collection agency
Send it certified mail, return receipt requested. Keep the green card. When a collector claims it never got your letter, that card ends the argument.
Heads up: if it's the original creditor coming after you — your landlord, your hospital — § 1692g doesn't force them to validate anything. Send the itemization demand anyway. Then lean on § 559.72(9) and your own records.
Step 3: Pull your own receipts — especially on rent debts
This is where my Pine Hills client won.
Florida has a strict rule on security deposits. Under Fla. Stat. § 83.49, a landlord who wants to keep any part of your deposit has 30 days after you move out to send you written notice of its claim by certified mail. If the landlord misses that deadline, it forfeits the right to impose a claim on the deposit.
Her complex never sent that notice. Not on day 30, not on day 90.
So we built the dispute around the math and the statute:
- Her full deposit had to come off the balance
- The complex re-rented the unit two weeks after move-out, so it couldn't keep billing her for months a paying tenant already covered
- Once you applied both credits, the $2,100 didn't hold up
We disputed the inflated balance with the collector and with all three bureaus, and we cited § 559.72(9) — you can't enforce a debt you know isn't legitimate. It didn't happen overnight. It took more than one round of letters and some follow-up with the bureaus. But the balance got corrected to $0.
I can't promise every rent collection ends that way. Some landlords do the paperwork right, and a legitimate, accurate balance is a legitimate balance. But I'd guess half the apartment collections I see across Central Florida have at least one accounting problem worth disputing. (I wish I was kidding.) The same three show up over and over: a deposit that never got credited, rent billed for months after a new tenant moved in, and "cleaning" or "repainting" fees nobody can document.
This kind of dispute is exactly what our collections removal service collections removal handles — challenging inaccurate and unverifiable collections, not legitimate ones.
Step 4: Dispute the credit reporting separately
Fixing the debt and fixing the report are two different fights. Here's what actually happens when you dispute online: the bureau converts your dispute into a short code and ships it to the furnisher through an automated system called e-OSCAR. Your carefully written explanation often gets boiled down to a two-digit reason code.
That's why I tell clients to mail disputes with supporting documents — the 83.49 timeline, the move-out date, the new tenant's lease start if you have it. Under FCRA § 611 (15 U.S.C. § 1681i), the bureau generally gets 30 days to investigate, and it has to forward your relevant documents to the furnisher. If you send in more information during that window, the bureau can stretch it to 45 days.
Step 5: Put collectors on notice — in writing
If the calls keep coming, send a written letter telling the collector to stop contacting you (federal law gives you this right against third-party collectors) and naming the specific Florida violations you've logged. List dates and times. Collectors' compliance departments read these. Some will correct a file just to make an FCCPA problem go away.
Step 6: Report it — and get the right help
You can file complaints with:
- The CFPB's complaint portal
- Florida's Office of Financial Regulation, which oversees registered consumer collection agencies
If you've got documented violations and actual damages, talk to a Florida consumer protection attorney. Many take FCCPA and FDCPA cases because the statutes allow attorney's fee awards. Remember the two-year clock under Florida law — and one year under federal law — starts at the violation.
If you got served with a lawsuit, respond within 20 days. Don't wait for a better time. There isn't one.
Talk to a Real Credit Specialist — Free
The fastest way to get straight answers about your situation in Orlando and across Florida.
4.9 · 89 Google reviews · No upfront fee
Call (407) 606-7117Individual results vary. We help you dispute inaccurate, unverifiable, or outdated items — no one can remove accurate, current information from your credit report, and you can dispute it yourself for free with the bureaus.
Collector won't back off? Call Freedom Credit Repair at (407) 606-7117 and bring your call log.
Why Florida Workers Get Hit Harder
Honestly, most people don't realize how much the local economy feeds these collection messes.
Disney and Universal cast members get paid biweekly. Hospitality workers on I-Drive watch their hours drop every September when the parks slow down. Nurses and techs at AdventHealth and Orlando Health pick up shifts one month and lose them the next. Autopay schedules built around steady paychecks fall apart, a rent payment bounces, and three months later a collector's on the phone with fees stacked on fees.
That's not a character flaw. That's a math problem — and inflated balances are often hiding inside it. Our Florida credit repair credit repair across Florida work focuses on exactly these real-world situations, and if you're local to Pine Hills, Lake Nona, Winter Park, Sanford, or anywhere in the metro, our Orlando credit repair credit repair in Orlando team knows how Orange County apartment complexes and collectors actually operate.
Do It Yourself or Get Backup?
You can dispute inaccurate items with Equifax, Experian, and TransUnion for free, and you can send validation letters yourself. Nothing in this post requires paying anybody.
Where people call us is when the collector won't quit, the balance math is a mess, or they're trying to get approved for a mortgage and can't afford a six-month detour. We get questions about timelines and pricing constantly — check our FAQ for the full breakdown.
We can't guarantee any specific result, and nobody legitimately can. What we do is build documented, statute-backed disputes against inaccurate, unverifiable, or outdated items and help you push back on collectors who cross the line.
If a collector's been leaning on you, call Freedom Credit Repair at (407) 606-7117. We're in Orlando and work with clients all over Florida by phone. Bring your call log.
FAQ: FCCPA Florida Debt Collection
Does the FCCPA apply to original creditors in Florida?
Yes. The Florida Consumer Collection Practices Act applies to any person collecting a consumer debt, which includes original creditors like landlords, hospitals, and credit card issuers. The federal FDCPA generally covers only third-party collectors, so this is one of the biggest gaps Florida law fills.
How much can you sue for under the FCCPA?
A court may award actual damages, up to $1,000 in additional statutory damages, punitive damages at the court's discretion, plus court costs and attorney's fees under Fla. Stat. § 559.77. None of it's automatic — collectors can raise a bona fide error defense, and a court can award fees against you if your claim lacks a justiciable issue.
How long do you have to file an FCCPA claim?
You have two years from the date of the violation to file a lawsuit under the FCCPA. That's double the one-year window under the federal FDCPA, so keep dated records of every call and letter.
What hours can debt collectors call in Florida?
Debt collectors generally can't contact you in Florida between 9 p.m. and 8 a.m. your local time without your prior consent. Federal law uses the same hours for third-party collectors, but Florida's rule covers original creditors too. Florida law also bars calls so frequent that they're reasonably expected to harass you.
Can a collector report an inflated balance after a broken lease?
A collector can't knowingly try to enforce a debt that isn't legitimate under Fla. Stat. § 559.72(9). If your landlord didn't follow the 30-day security deposit notice rule in § 83.49, or kept billing you after a new tenant moved in, you can dispute the balance with the collector and the credit bureaus, using your documents as evidence.

Matt Brody
Founder, Freedom Credit Repair
Matt is the founder of Freedom Credit Repair based in Orlando, FL. Since 2019, Matt has helped clients remove negative items from their credit reports and take control of their financial future. Call (407) 606-7117 for a free consultation. More about Matt →